MCF Market Watch


Welcome!


In the interest of keeping our clientele educated and well-informed in a trying economy, MCF issues bi-weekly market assessments.

Go to our web site to subscribe to this and other news and tools, including the MCF Rate Sheet and Mortgage Solutions - Real Quotes On Real Deals (TM).

Follow us online! 


Monday, May 10, 2010

Greece: Standing Alone?

Doug Marshall, CCIM
Market Assessment
Published May 4, 2010

On April 27, Greece had their bond status cut by Standard and Poor’s, downgraded to ‘junk’ status, which set off a chain reaction in stock markets throughout the world.

On the same day Portugal, too, had their bond rating reduced. A day later, Spain’s debt got classed lower, from AA+ to AA. Who’s next?

The critical question is whether the proposed bailout action being worked up now going to be sufficient to keep Greece out of default on its European Union obligations?

The approach to Greece seems to be attempting to redress two rather co-dependent issues: 1) how to keep the “contagion” from spreading, through a massive combined bailout effort and a drastic tightening of the Greek belt through austerity measures, and 2) how to infuse confidence in euro debt-holders around the world who have dropped European debt like they were holding hot coals.

Jean-Claude Trichet, European Central Bank president, said a Greek default was “out of the question”. But several market analysts with MarketWatch.com, of the Wall Street Journal, suggest that the EU go ahead and cut Greece loose.

It is being argued that expulsion from the EU is not a terrible or irresponsible idea, in that the contagion spreads no further and Greece learns a lesson over the next few years while it gets its collective house in order.

It’s clear that one whisper of default causes many debt-holders to run for the door. But people seem to question whether this situation should be seen as an emergency encompassing the entire EU, simply because EU confidence and influence create domino-like effects. Or should it be considered as Greece problem and spare the rest of the EU shares in its drama?

But while these analysts suggest that the Greek situation and its long-term effect on the euro and world stock markets may be exaggerated, there is no exaggerating the way in which institutional investors have responded to Greece’s financial woes.

The euro has dropped to a new one year low compared when compared to the dollar and is continuing to fall in value. Since mid-2008 the euro has lost a whopping 16 percent of its value when compared to the dollar.

More importantly, from our view point as Americans, investors around the world are buying U.S. Treasuries, which is the typical “flight to quality” that occurs during times of crisis. This increase in demand of U.S. Treasuries has caused interest rates to drop significantly during the past few weeks.

The 10 year treasury was recently above 4.0% and at the time of this writing is now at 3.59%. This bodes well in the short run for our economic recovery as the crisis in Greece will keep our interest rates lower than they would otherwise be.

One thing is certain: comparisons are easy, but the reality is harsh. Barring a removal from the EU by the governing body, a numbing idea, Greece and other nations will have no choice but to issue more and more debt holdings in order to survive.

And who is buying those these days?

Sources:
David Oakley, Alan Beattie, Kerin Hope; “IMF Looks At Offering Greece More Cash”, FT.com April 27 2010
Jon Markman, “Let Greece Default On Its Debts”, MarketWatch.com April 28 2010
Nicholas Kulish, “Europe Looks To Aid Package As Spain’s Debt Rating Is Cut”, The New York Times April 28 2010

Tuesday, April 27, 2010

We Have A Heartbeat!

by Doug Marshall, CCIM
Market Assessment


It’s become a cliché: “The economy is recovering! The rebound is here!”

But after reading many reports like this, sometimes based on spotty evidence and flimsy source material, it’s still a large and looming question. Are we seeing real growth, and if so, is a recovery happening in the Pacific Northwest?

If growth, wouldn’t that be encouraging for those of us who’ve been waiting for something to cling our hopes on? The $800 billion government stimulus package, encouraging spending and protecting business, is beginning to show some positive results.

Consumer spending has increased around 4 percent in the first quarter of this year; new home sales increased 27 percent; and exports jumped in the first two months of the year by 15 percent, as compared with the previous year. All this has occurred as household debt has declined by $600 billion since the fall of 2008.

Surely this means that we’re seeing recovery, optimists say. And that would be a very, very good thing for a commercial real estate market facing billions of dollars in loans requiring refinancing, or at least major modification.

Where is it going to come from? This very important question is still left unanswered with no apparent solution in sight.

But it appears that this is a real, sustainable recovery we’re seeing. Consumer spending is a great indicator of economic recovery. Any indicator that comprises 70 percent of American economic activity is sure to be that.

But that still doesn’t answer the question: What is the health of the commercial real estate market while people shop Amazon for iPads or go shopping for a new car?

Even the real estate market is showing positive indicators that we’ve gone through the worst of it and are coming out the other side as evidenced by:

· Citigroup, who recently put together a $222 million AAA-rated RMBS pool to Wall Street. That’s very modest in terms of the size of the mortgage pool when compared to just a few years ago, but it’s progress nonetheless.

· REITs have had a robust increase in the value of their stock over the past year as they have taken advantage of acquiring real estate at depressed prices.

· The CMBS market, such as it is, is eking out more substantial packages. They remain low in dollar amount by comparison with previous years, but the trend upward is a positive sign.

There are qualifications to the reported activity, of course. The CMBS process still remains, according to some REITs in the mix, “laborious and painful, hardly worth the effort”. But it’s a market that has gotten slowly to its feet.

The question now is whether employment and income, other indicators required to round out the “recovery” rally, are making the same effort or experiencing the same improvement.

Ah, there’s the rub.


Sources
:
Peter S. Goodman, The New York Times, April 25 2010;
Erika Murphy, GlobeSt.Com Beltway Buzz, “Another Win For CMBS – and REITs,” March 24 2010;
Erika Murphy, GlobeSt.Com Beltway Buzz, “Four Signs Of Life In The Past Week,” April 22 2010

Tuesday, April 13, 2010

The Impact of the Exploding Federal Deficit

Doug Marshall, CCIM
Market Assessment

Set aside all the arguments for or against the recently passed health care bill. There are good, altruistic people on both sides of the debate that want what’s best for this country.

Forget all that and simply ask yourself this: Where’s the money to pay for it?

Take a look at this simple but frightening chart whose sources are the Congressional Budget Office (in red) and the White House (in orange).

What they are reporting is the best possible scenario – the most optimistic projection that anyone can come up with.

Also remember that whenever Congress passes a new entitlement program
, without exception, its estimated cost is always substantially underestimated.

Here’s what the graph summarizes. The Bush administration inherited a surplus from the Clinton years.

But tax cuts, the response to 9/11, and a Republican Congress that spent money like drunken sailors drove the federal government into deficits of around a third of a trillion dollars, annually.

Then, in 2008, the Democrats’ first year in charge of Congress took the deficit up toward half a trillion dollars. Then came the unprecedented deficit of 2009, the year of the financial meltdown on Wall Street and the near collapse of the financial services sector worldwide.

Arguments can be made that some of this spending was absolutely necessary to avoid an economic catastrophe. I am willing to give the Democrats the benefit of the doubt. We will never know for sure.

But now focus on the remaining part of the graph – the years going forward. The projections, mind you, are what the sponsors of “health reform” say will happen if everything goes right for the next 10 years – if all the optimistic assumptions work just the way they hope they will.

By their own forecasts, the money isn’t there.

So what’s the solution? Can we grow our economy fast enough to avoid these deficits? I don’t believe so. Can we tax ourselves to a balanced budget? Not possible.

Do our politicians have the political will to make difficult spending decisions that would reduce our outlays in entitlement programs like Medicare, Medicaid, Social Security, and now health care?

Don’t count on it.

What other alternatives are there? There are really only two: 1) Borrow at levels that are unprecedented in size at a time when the global buyers of our paper – China, Japan and other countries - are beginning to slow their purchases of our US Treasury bills; or 2) expect massive hyper-inflation caused by the government’s ability to print money.

Dr. John Baen, a professor at the University of North Texas, recently spoke to a commercial real estate conference in southern Oregon.

He predicts a 20% chance of a depression and an 80% chance of hyper-inflation, with very little chance of something in between.

Not a rosy picture... My bet in on inflation and, if that is true, how do you best prepare yourself and your clientele for such an event? Historically, what assets benefit during times of inflation?

One of them is real estate of all kinds, but especially commercial real estate that is leveraged with long-term, fixed rate debt.

I believe that those who lock in long-term fixed rate loans before interest rates inevitably begin to rise are going to be the big winners in this coming era of out of control federal deficits.


Sources:
It Takes Money by
Joel Belz, World magazine, April 10, 2010
Comments by Dr. John Baen at the Southern Oregon Real Estate
Marketing Conference, April 1-2, 2010.

Thursday, April 1, 2010

It’s The Same All Over

As Yogi Berra once said, “It’s déjà vu all over again.” Actually it’s “sì céng jiàn guò”. And not in a good way...

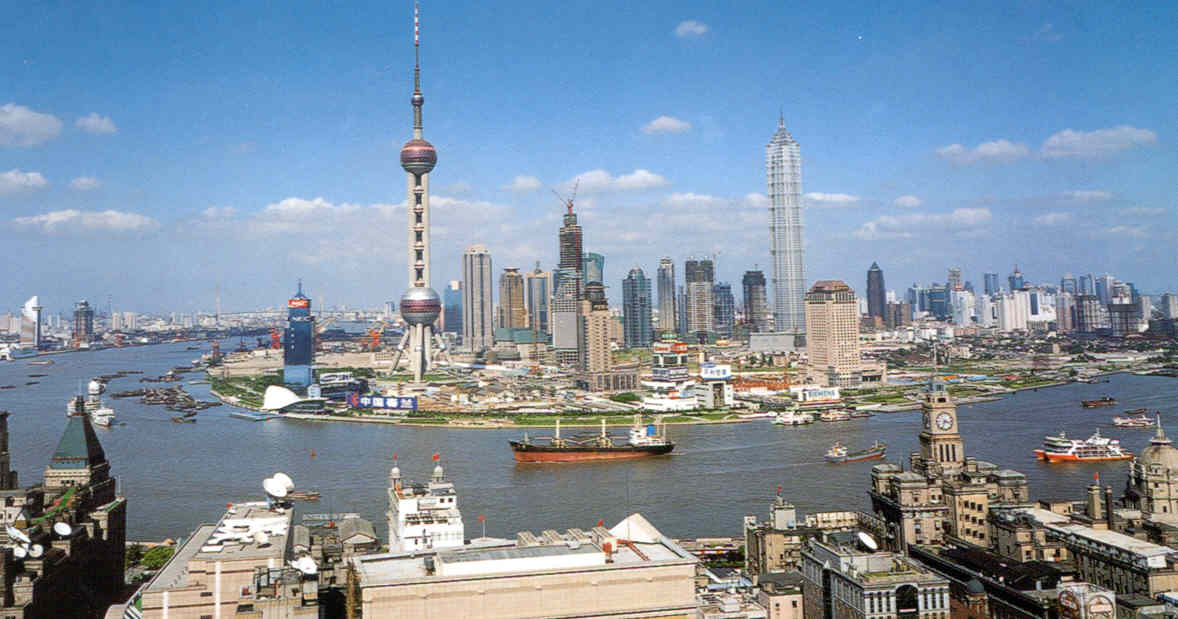
The problem? The real estate market in China has exploded across this nation. In China these days apartments and property, of any kind, are selling so fast that demand has exceeded supply in many places.

Prices are skyrocketing and prospective homeowners are hurriedly buying up anything they can afford – and a lot that they can’t. Does this sound familiar?

The resultant bubble, many economists and government officials fear, looms over the nation’s state-owned industries, banks, developers, and commodities suppliers like a cloud. And the question is not if the bubble will burst, it’s when.

The concern that is exhibiting itself in every economic circle of thought isn’t limited to the ramifications that the popping of such a bubble would have on China’s economy. The effect of such a burst would have worldwide implications.

Over that past couple of decades, economies across the world have been buoyed by China’s robust market. China’s economic growth this quarter has been predicted by some to reach 12%. During the entire year a 9% growth rate is anticipated.

And yet, just as economic recovery appears to be taking hold in other nations, a collapse of the real estate market in China will threaten its demand for goods from other nations across the globe adversely impacting the feeble recovery here and abroad.

The real estate market in China has been the secret to the success there, in many ways. State-run developments and projects have continued to build massive housing projects, due to an insatiable demand which is fueled by rising prices of homes, apartments, and other properties.

Those who can afford it are buying homes to flip, as investments. And, reflecting the disparity of income levels within China, the poor are left without low-income housing consideration.

The rate at which these buildings – apartments and condos – are going up is simply astounding. Their locations often bewilder. Prices for high-end apartments, in Shanghai alone, rose 54% through September. Apartments across major cities will often cost between $300 and $500 per square foot – if you can get them.

It’s difficult to peg or predict where this trend is headed. The data is insufficient to create trends or predict between one quarter and another. And there are many facets to it, one ripple effect causing another.

One economist will predict a massive downturn one quarter only to be embarrassed by a huge upswing and larger gain than ever the next. Market analysts request that economists and prognosticators wait and see, watching the technicals that are still proclaiming China to be a safe bet.

Those of us who are living through our real estate crisis realize the consequences of a real estate bubble. How China’s real estate bubble will affect the world economy is anybody’s guess. Let’s hope that the Chinese do a better job controlling their situation than we did.


Sources
:
Dexter Roberts,
BusinessWeek
Bill Powell, Bharat Chronicle March 30, 2010
Mary Woo, Minyanville Business Markets, March 29 2010

Tuesday, March 16, 2010

The Oregonian Weighs in on Banking Crisis

by Doug Marshall, CCIM
Market Assessment


It is not often that I agree with an editorial written by The Oregonian Editorial Board. And it’s even less often when I just quote an article (it’s been shortened a bit) without comment. But this article is spot on and needs no comments by me. Please read this insightful opinion piece regarding the current commercial real estate banking crisis.


The Oregonian
March 7, 2010
“A wave of commercial real estate loan failures could threaten America’s already-weakened financial system,” begins a Feb. 10 report by the Congressional Oversight Panel, which gloomily predicts that losses at banks alone could reach $300 billion as more than $1.4 trillion in commercial real estate loans become due over the next five years.


This is leading to a massive recalibration of the commercial real estate market, and is likely going to spell a wave of foreclosures or distressed sales of commercial buildings. It also has the potential to undermine a swath of small and mid-size banks that made commercial real estate loans.

As the oversight panel put it, “their widespread failure could disrupt local communities, undermine the economic recovery and extend an already painful recession."

What to do?

The choices range, roughly, from writing down all the values to reflect current market conditions, which would likely spell the failure of many independent banks, to some sort of coordinated, TARP-like intervention by the federal government in the small-bank sector. Neither direction is promising or desirable.


A middle course would be to encourage lenders to work out with borrowers the terms of loans that have sunk underwater. This is precisely the course mapped out by a set of financial regulators last fall, but it doesn’t seem to be happening in any consistent way.

A policy statement issued by a coalition of regulatory agencies in October encouraged examiners to make it easier for banks and borrowers to work out under performing loans.

Yet independent bankers in Oregon complain that examiners haven’t relented on their demands that banks purge their balance sheets of underwater loans, or raise more capital in reserve. This has the effect of taking out of circulation money that would otherwise be lent to credit-worthy borrowers.

What’s best for the economy is that credit keep flowing, because it is the lubricant that makes it possible for businesses to hire people and buy equipment. We’re just coming out of a period when they were doing neither: we want to avoid driving ourselves into another recession.

There’s a growing tension between the forces of rigorous regulation and those who want to buy time to let lenders and borrowers work their loans, while hoping for a market rebound.

Washington Gov. Chris Gregoire, Rep. Barney Frank D-Mass., Sen. Chris Dodd, D-Conn., and others have expressed alarm about inflexible bank examiners, but market purists call that “extend and pretend,” and say it’s imprudent to allow banks to keep bad loans on the books without taking action.


A lot of loans shouldn’t have been made and deserve to be written down. But a massive, economy-wide write down will be destructive. It’s OK that some buildings will be sold at a loss and that some banks will be closed.

But the guiding principle for regulators, from senators to bank examiners, should be to keep credit flowing and follow no rule over a cliff, especially since valuation is an inexact science.


The bias should be toward survival. Close the banks that made too many imprudent loans, but don’t close the ones that deserve to survive, as angry shareholders of the wrongly seized Ben Franklin Savings and Loan would remind us.


Nobody wants to make a bad situation worse.


Banks in Path of Commercial Real Estate Crash, The Oregonian, March 7, 2010.