MCF Market Watch


Welcome!


In the interest of keeping our clientele educated and well-informed in a trying economy, MCF issues bi-weekly market assessments.

Go to our web site to subscribe to this and other news and tools, including the MCF Rate Sheet and Mortgage Solutions - Real Quotes On Real Deals (TM).

Follow us online! 


Friday, March 5, 2010

So Who's Financing Commercial Real Estate?

by Doug Marshall, CCIM
Market Assessment

Last week I showed you who in 2009 was lending on apartments. If you did not read that post and would like me to re-send it, please contact me.

This week I have the final results of who was lending in 2009 on commercial real estate sales transactions. But first I must define what I mean by commercial real estate.

I am referring to investor-owned real estate (not owner-occupied) and the property type could be office, flex, industrial, retail or shopping center.

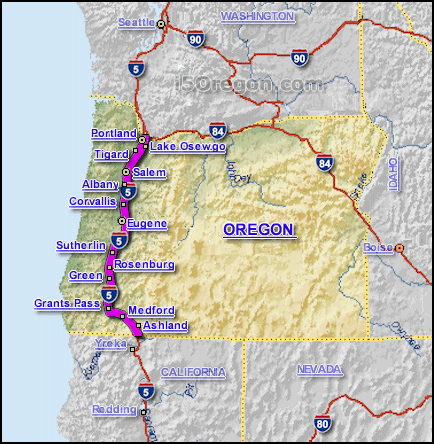
Last year there were 81 arms length commercial real estate sales that occurred along the I-5 corridor from Kelso, Washington to Eugene, Oregon including Bend that were $1,000,000 to $10,000,000 in size.

As was true with apartment lending, the lenders for commercial real estate sales were both surprising and predictable. 41% of all sales transactions were financed either by all-cash buyers, seller financed or private sources!

That’s huge!!!

This is a very real indicator of the lending crisis we are currently going through when traditional lending sources are not lending.

Another interesting tidbit is that 22% of all loans did not disclose any financial details. What’s with this?

My hunch is that these transactions were distressed sales. Either lenders foreclosed on borrowers or sellers sold under duress to buyers where loans were assumed.

Local and regional banks totaled 30% of the financing for commercial real estate sales. On the banking side of lending, there has emerged some very real winners as well as some very real losers. We’ve all heard about those lenders that have been taken over by the FDIC.

Another interesting statistic is that over two-thirds of Oregon banks were not profitable last year. However, 2009 proved to be very profitable for a small group of lenders both regional and local.

The key to borrowing these days is to know which banks are still lending and which ones have the most competitive rates and terms.

As was true with apartments, life company lending was virtually non-existent in 2009 with only 2 transactions. I keep hearing that the life companies are back but that has yet to be proven by the statistics.

Please contact me if you have any questions, or better yet, if you have need for a loan quote on your next transaction.

So Who's Financing Apartments?

The final results of all apartment sales transactions for 2009 have been tabulated.


The CoStar Group identified 65 arms length apartment transactions that took place along the I-5 corridor from Kelso, Washington to Eugene, Oregon including Bend that were $1,000,000 or more in size.

As a mortgage broker my primary interest is who financed these 65 transactions and do I have access to these lending sources?

The results are both surprising and predictable:

Thirty percent of all the sales transactions were either all cash buyers, seller financed or private individuals.

That seems like a huge percentage! I wonder how that compares to previous years? My guess is that this percentage is substantially higher than a typical year when financing is readily available.

The federal agencies, Fannie Mae, Freddie Mac and HUD comprised 24% of the financing for apartments.

Fannie Mae was the primary lender of the three but Freddie Mac’s strategy was to do the larger transactions so loan volume between the two was very similar.

Even with the 35 year fully amortizing loan with no balloon and a reasonable step down prepayment penalty HUD could not overcome the negatives of financing with them: 6 to 9 months to close, and substantially higher closing costs.

Local and regional banks totaled 34% of the financing for apartments. This did not come as a surprise to me.

If a borrower wants a five year fixed rate loan, 30 year amortization at a reasonable rate it’s the banks that will be the most likely to come through.

But the key is to know which banks are the most competitive.

Surprisingly, no apartment sales were financed by the life companies. When it comes to apartment financing, life companies are generally not competitive with Fannie Mae or Freddie Mac.

Thursday, February 18, 2010

My Big, Fat, Greek Financial Crisis

by Doug Marshall, CCIM
Market Assessment


And we thought we had problems...

The global financial crisis continues to rock governments and shake all sectors of life. Right now, it’s Greece who faces the biggest challenge that a country could: default on a national scale.

Over the past two weeks, Greece has come under massive attack from the European Commission, global banking and capital market institutions, and its own populace.

Loaded with a whopping GDP deficit of 12.7 percent, the EU has given the country’s financial minister and government three years in which to cut, slash, and tax its way to less than 3 percent.

If it can’t perform? Could it be expelled from the euro zone? Improbable. Could it suffer further ignominy and lose what’s left of its credibility? Very likely.

Parallels have even been drawn between the sovereign nation, embroiled in financial discredit and debt, and investment bank Bear Stearns, rescued by the Federal Reserve two years ago.

But the discussion surrounding this topic, especially from the executive of the European Commission, doesn’t seem quite as forgiving with Greece as The Fed was with Bear Stearns.

While European nations have indeed pledge to aid Greece “if needed to guard financial stability in the euro area”, the Commission is not about to approve the underwriting of a struggling nation without requiring proofs of action on the part of Greece to attempt the correction its promised.

“It will be up to the Greeks to prove that the existing adjustment program will be sufficient,” stated Luxembourg Prime Minister Jean-Claude Juncker. And the Commission has already warned Greece that, despite protests nationwide and strikes by public workers, it would keep a tight rein on and require another check in March to verify compliance.

Greece’s instability has already helped in recent months to torpedo the value of the euro, which has slid to a nine-month low against the dollar.

But Greece’s Finance Minister George Papaconstantinou stresses that the effect of default by Greece would not create difficulty for the euro zone as a whole, the nation representing only two percent of the euro area’s economic output. “Today it’s Greece, tomorrow it could be another country”, says Papaconstantinou.

How Greece came to this is complicated and requires another discussion.

The European Commission has expressed outrage at the possibility that enormous debt might have been hidden through the use of currency swaps brokered by Goldman Sachs and others… there’s another matter altogether.

One national falter at a time!

Sources:
Rob Cox and Rolfe Winkler, Reuters’ Breakingviews.com, 2/11/2010
Aoife White, AP Press, 2/15/2010

Thursday, January 21, 2010

2010 ULI Forecast (Part 2)

In my last market assessment, I summarized some salient points in the 2010 commercial real estate forecast presented in Emerging Trends in Real Estate.

This publication is a joint undertaking by the Urban Land Institute and PricewaterhouseCoopers. It reflects the views of more than 900 real estate professionals and is considered one of the best researched real estate periodicals of its kind.

This week’s market assessment covers their predictions for commercial real estate financing for the coming year. Their forecast:

  • Banks will become willing lenders only when they have more equity or more earnings. In the meantime, an increasing number of “zombie banks” will be on the sidelines. For 2010, it’s survival of the most liquid. Surviving banks will start to dispose of real estate owned.
  • Hundreds of banks could fail, particularly regional and community banks with significant exposure to homebuilder, land and construction loans, resulting in government regulators packaging and selling more bad loans.
  • Those banks who will be lending will employ stringent underwriting to limit transactions. Sponsorship quality and longstanding, banker/borrower relationships will be the primary requirement to obtain loan approval.
  • The CMBS market is described as a “huge time bomb” wrapped in a “ball of confusion.” Securitized loans will remain entangled in complex workouts of failed multi-tranched structures and many of these loans will go into monetary defaults before maturities because of borrower financial issues and lagging fundamentals.
As grim as this forecast is, I am beginning to see anecdotal evidence that the Portland lending market is turning a corner.

Since the beginning of the year I have talked with two local lenders who are actually hiring to beef up their commercial lending departments – Umpqua Bank and Northwest Bank. I’ve also talked with a couple other lenders who have loosened their loan underwriting standards a bit making it slightly easier to get a loan.

And then there are several other lenders who are talking like they are ready to come back into the market, which reminds me of the well known Texas saying, “Are they all hat and no cattle?” Who knows? We’ll have to wait and see.

No one has ever accused me of being Mr. Optimist but I believe our current lending environment is not all doom and gloom. We’ve got a long way to go before we reach a lending environment that approaches “normal” but I’m seeing baby steps in that direction.

Hang in there! There will be an end to this lending crisis.

Tuesday, January 12, 2010

2010 ULI Forecast – It Ain’t Pretty (Part 1)

Emerging Trends in Real Estate is a trends and forecast publication undertaken jointly by the Urban Land Institute and PricewaterhouseCoopers.

This publication is considered by many as the best researched real estate periodical of its kind. Their 2010 edition reflects the views of more than 900 real estate professionals. Their forecast for this coming year isn’t pretty; in fact to be blunt, it’s downright ugly.

I have divided their forecast into two parts – today summarizes their 2010 predictions for commercial real estate. The following week will focus on their thoughts about financing trends for the coming year.

For the weak-hearted, you may want to stop reading any further. Their forecast:

  • The commercial real estate industry will hit bottom in 2010. Values will ultimately decline 40 percent of the mid-2007 pricing peak making it the worst decline in property values since the Great Depression.
  • A lackluster economic recovery characterized by problematic job growth will hamper the pace of any real estate market resurgence.
  • Rents and occupancy rates will continue to fall well into 2010 further hurting prospects of weakened owners securing financing on properties where loans come due during the year.
  • Retail and office properties will take the biggest hits. Debt burdened consumers will continue to rein in shopping and companies will delay hiring while looking to shave occupancy costs.
  • Apartments should rebound more quickly than other sectors thanks to pent-up demand from the expanding population of young adults tired of living with parents or roommates.
  • Developers will go on enforced holidays. Slack demand will push up vacancies and many new projects will not meet leasing projections or debt service obligations. In many markets values will sink well below replacement costs. Development doesn’t pencil out when investors can buy existing real estate at bargain basement prices.

I believe that 2010 will be a watershed year for those of us in the commercial real estate industry. As bad as the market has been, we have not seen a proportional number of people getting out of the business as I would anticipate.

That will change this year. Those who have been hanging on by their fingernails will either make deals happen or will decide it’s time to find another profession.

For those of us who survive this year we can take solace in the words of the great philosopher Friedrich Nietzche: “What doesn’t kill us makes us stronger.”

Source:
Emerging Trends in Real Estate 2010,
Urban Land Institute & PriceWaterhouseCoopers.